







Buying insulating shades in 2025 did not make the purchase eligible for the federal section 25C credit. The IRS's January 2025 FAQ specifically excludes window treatments. A thermal label, cellular construction or manufacturer statement is not a basis for treating those shade costs as qualifying exterior windows.
If you are reviewing a 2025 invoice, start by separating the products and work it actually covers. This guide explains that record-checking task. For a new purchase, compare energy-efficient shades for comfort and operating value without assuming a federal tax reduction.
Separate window treatments from other window-area work
A single room project may include shades, exterior windows, trim repairs, installation and electrical work. Those are different items. A description such as “window upgrade” does not establish one tax treatment for the whole invoice.
Find the model names, product descriptions and separate charges. If the bill is unclear, ask the supplier or installer for a more detailed breakdown. A tax preparer can then evaluate the relevant items rather than relying on the room where they were installed.
The same approach helps with service later. Clear records show which shade, fabric, lift and mounting work were supplied, even when no incentive applies.
Do not use a shade rating as an eligibility shortcut
There is no cellular cell-count or shade R-value threshold in this guide that makes a window treatment eligible under section 25C. Do not substitute a thermal test, emissions certificate or brand name for the actual program rules.
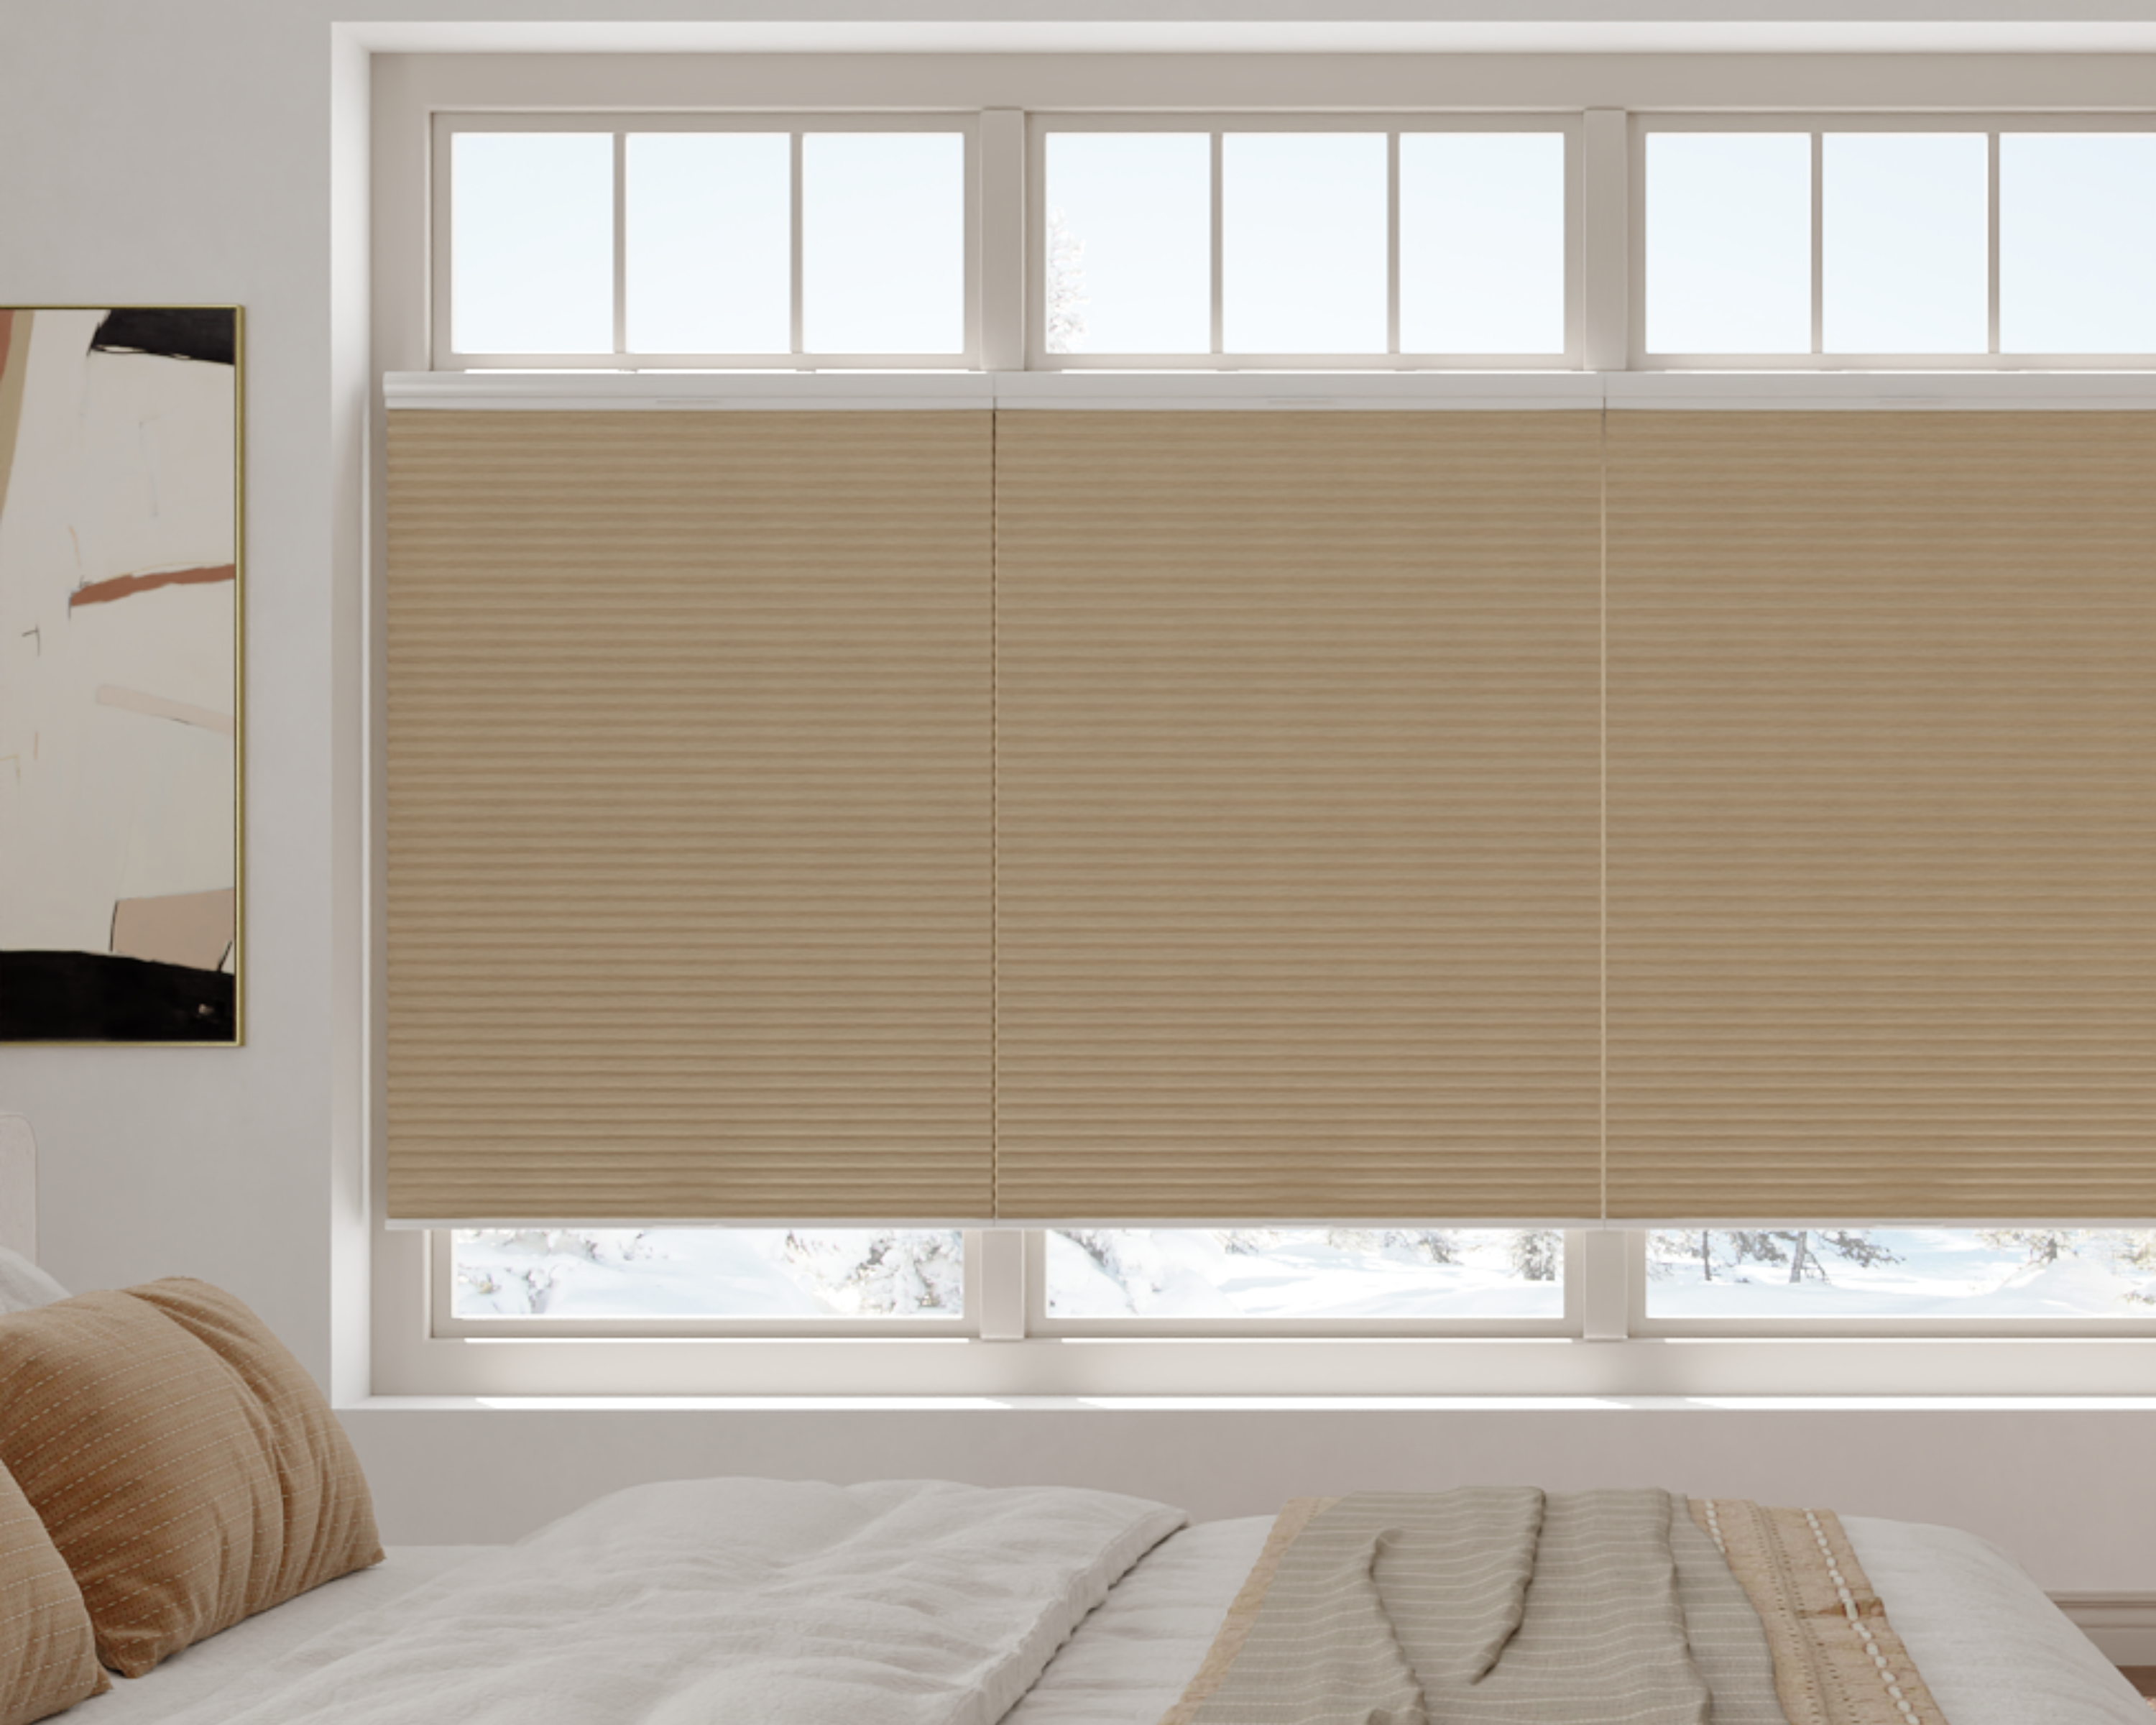
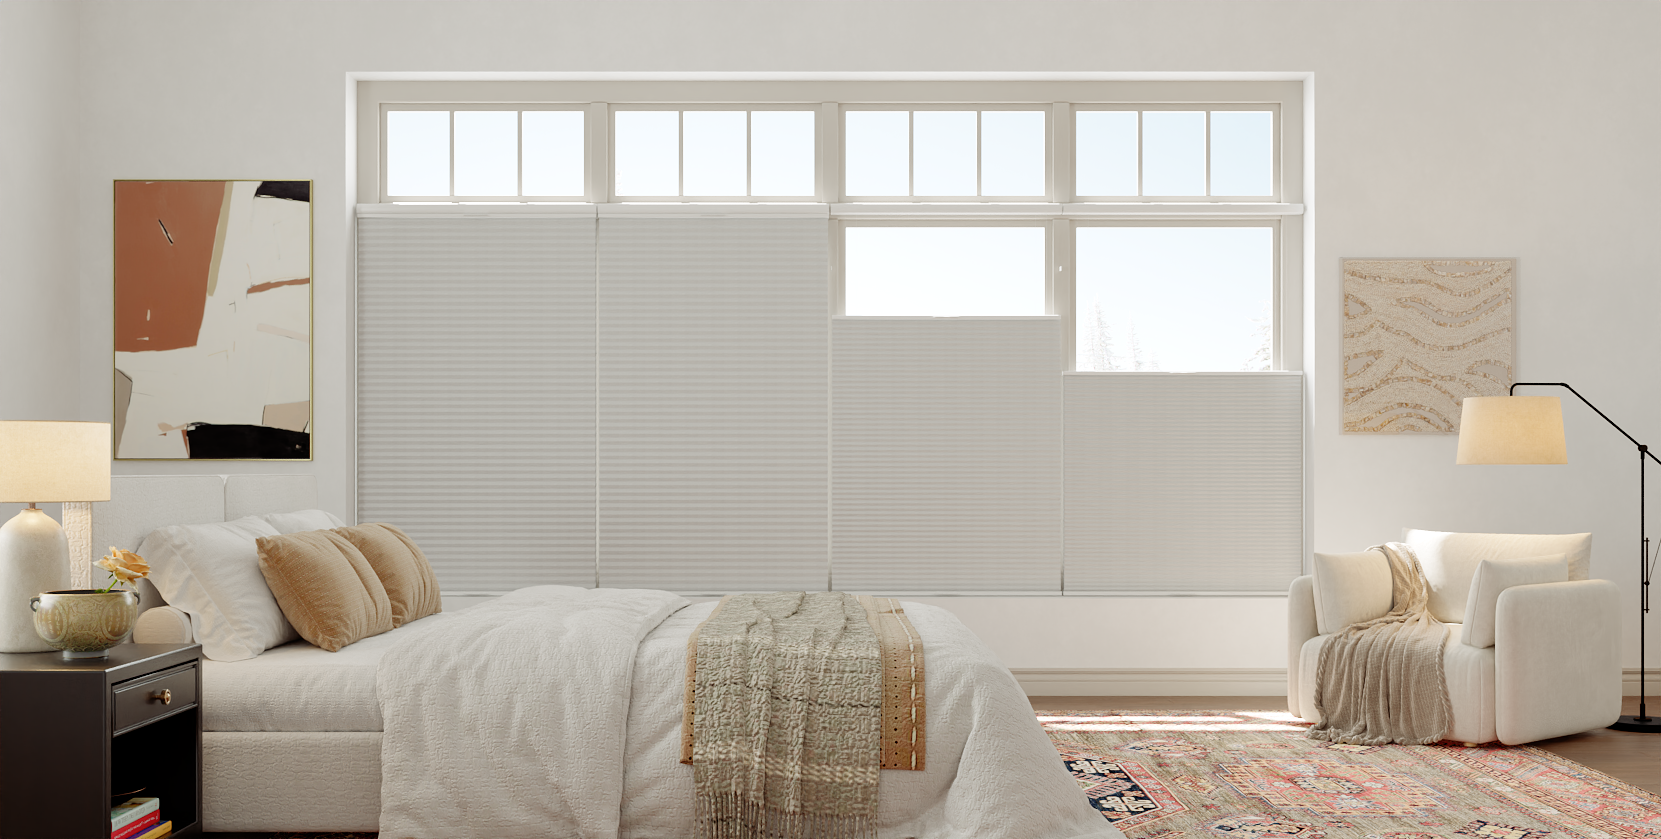
When you compare cellular shades, air-cell design and fit remain useful comfort considerations. Likewise, a roller fabric's opacity or reflective surface may matter to a sunny room. Those product differences should be assessed separately from any tax claim. Our cellular-versus-roller insulation comparison explains the construction choice.
If a quote or advertisement promised a tax benefit, keep a copy and ask which official rule supports it. Do not assume a list of supposedly eligible brands applies to your purchase.
A practical review folder for a 2025 purchase
Collect the documents that identify the transaction and make the discussion with your preparer specific:
| Record | What it establishes |
|---|---|
| Itemized invoice | Which products and services you purchased and their separate costs. |
| Model and fabric selection | The identity of the shade, rather than a broad collection name. |
| Installation record | What work was completed and when. |
| Written incentive terms | The administrator and exact conditions of a claimed rebate or other program. |
| Supplier correspondence | Any product or eligibility representations you need clarified. |
These documents are useful records, not automatic proof that the shade qualifies for a credit. Ask your tax professional how to handle a previous claim or an invoice containing several types of work; this article does not provide instructions for an individual return.
Check the date of the rule you are reading
Old energy-credit articles can describe rules that have changed. The IRS's later termination guidance states that section 25C is unavailable for property placed in service after December 31, 2025. That timing change is separate from the window-treatment exclusion already stated in its January 2025 FAQ.
When reviewing another home improvement, use the rules for that item and the relevant period. A 2025 purchase record and a 2026 installation plan are different situations. Do not carry an old percentage, deadline or product list into a new project without checking the current official guidance.
Treat local rebates as separate programs
A utility, local authority or other program may have its own scope. Verify any proposed benefit with its official administrator rather than inferring it from federal tax language or a retailer's category label.
For a past purchase, ask whether the program covered the product, address and installation period and whether advance approval was required. For a future order, get those answers before placing the order. Do not assume an incentive can be added retrospectively or combined with another offer.
Retailer discounts are another separate comparison. Judge a sale against an equivalent specification, including size, fabric, lift and installation, so a lower starting price does not hide a different configuration.
Keep the comfort decision useful even without a credit
Shades are worth comparing for the room problem they solve. Insulating cellular construction may suit a cold-feeling window; a glare-control fabric may suit a bright home office; opaque coverage may be the priority in a bedroom.
Fit and operation belong in that comparison. Measure for the selected system, allow for handles and recess depth, and choose controls you can use comfortably. Operate the covering to suit sunlight, daylight and privacy rather than expecting a material label to deliver a fixed bill reduction by itself.
When comparing quotes, use the full installed price before an unconfirmed incentive. This gives you a realistic starting point for choosing energy-efficient window shades.
Frequently asked questions
Which cellular brands qualified for the federal shade credit in 2025?
Do not rely on a brand list. The IRS FAQ excludes window treatments from section 25C; a brand name or insulating design does not remove that exclusion.
Does this mean a shade cannot improve comfort?
No. Tax eligibility and product performance are separate questions. Compare the selected fabric, construction, coverage and installation for your window.
What if I already included shade costs on a return?
Bring the invoice and the official IRS guidance to a qualified tax professional. They can review your circumstances and advise on the appropriate next step.
Where should I start if I am buying shades now?
Use our current guide to window shades and federal tax credits, then compare the products on comfort, privacy, operation and total installed cost.
